 Facebook
 X
 Pinterest
 Copy Link
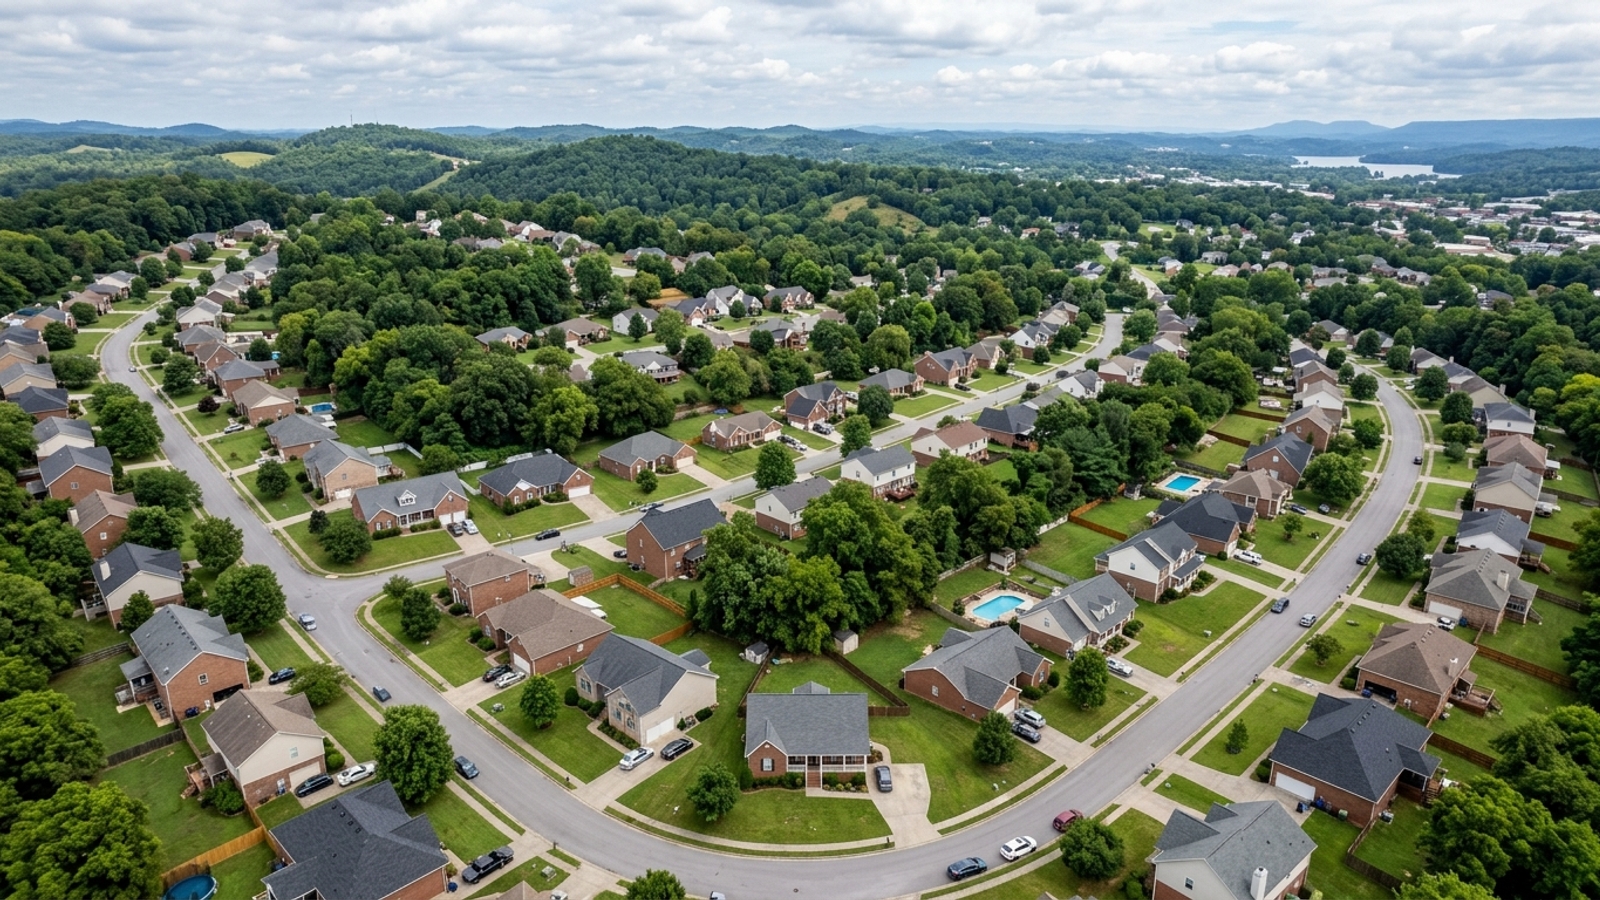
The median sale price for homes in Morristown, TN sits at approximately $308,375, and right now buyers are watching properties sit on the market for about 103 days. With roughly 121 homes available, you’ve got more breathing room to evaluate your financing than you did a few years ago. This extra time is a big advantage for first-time home buyers in Morristown, TN. That said, the loan you land matters just as much to your monthly budget as the house itself – especially here in Hamblen County, where property taxes can move the needle on what you can actually afford.
As of August 2026, the average 30-year fixed mortgage rate in Tennessee is running between 6.7% and 6.75%. That number shapes your payment every single month. Knowing how local assistance programs work, how different lenders price their loans, and what drives your specific quoted rate can easily be worth thousands of dollars over the life of your mortgage.
Today’s Mortgage Rates in Morristown
The Federal Reserve steers the broader market, but Tennessee rates track closely with national averages. NerdWallet and Zillow both report state averages in the mid-to-high 6% range for a standard 30-year fixed loan. Your actual quoted rate will depend on which loan product you choose – and your own financial profile.
Buyers in Morristown typically choose between fixed-rate and adjustable-rate products based on how long they plan to stay in the home. Lenders quote an Annual Percentage Rate (APR), which bundles the interest rate together with broker fees and some closing costs. That APR gives you a truer read on what the loan actually costs you.
30-Year Fixed Mortgages
The 30-year fixed remains the most popular option for Morristown buyers. Spreading payments over three decades keeps the monthly obligation lower, and as of mid-August 2026, Tennessee’s average sits between 6.7% and 6.75%. For a $308,375 home, that stability matters – your principal and interest payment is locked in and will never change.
15-Year Fixed Mortgages
If paying the home off faster and cutting total interest paid is the priority, the 15-year fixed is worth a hard look. Rates on these loans are currently averaging between 6.0% and 6.13% in Tennessee. The monthly payment is higher, but the long-term savings compared to a 30-year term are substantial.
Adjustable-Rate Mortgages
An adjustable-rate mortgage (ARM) typically offers a lower introductory rate for the first five or seven years, then adjusts annually based on market conditions. If you’re planning to sell or refinance your Hamblen County home before that introductory period ends, an ARM can mean real monthly savings upfront. Once the fixed period expires, though, your rate and payment move with the market.
What Influences the Rate You Get
A lender’s lowest advertised rate is generally reserved for borrowers with top-tier credit and a 20% down payment. Your actual quoted rate will reflect your specific financial profile and the details of the property you’re buying. Even small differences in your application can shift the rate by a fraction of a percentage point – which adds up fast over 30 years.
Underwriters are fundamentally evaluating risk. They look at your credit history, the size of your down payment, and the type of property you’re purchasing to land on a final rate and set of terms.
Credit Scores and Tiered Pricing
Your credit score carries more weight than any other single factor. Borrowers above 740 generally see the best terms; lower scores trigger loan-level pricing adjustments that push the rate up. Before you apply for pre-approval, pull your credit report, look for errors, and pay down revolving balances where you can.
Down Payments and Loan-to-Value Ratios
The loan-to-value (LTV) ratio compares your loan amount to the home’s purchase price. A larger down payment lowers that ratio, reduces the lender’s risk, and often earns you a better rate. Put down less than 20% on a conventional loan and you’re also adding private mortgage insurance to your monthly costs – until you’ve built enough equity to drop it.
Property Type and County Taxes
Rates can shift depending on whether you’re buying a single-family home, a townhome, or a multi-unit property. Lenders also fold local taxes into your debt-to-income ratio to confirm you can carry the full housing expense. Hamblen County’s effective property tax rate is estimated between 0.46% and 0.54% – on the lower end, which helps keep your total monthly obligation manageable.
Local Programs for First-Time Buyers
First-time buyers in Tennessee have access to state-backed programs built to make purchasing more affordable, typically by pairing competitive rates with down payment assistance to reduce the cash you need at closing.
There’s no down payment assistance program exclusive to Hamblen County, but Morristown buyers can absolutely use statewide resources. These programs exist specifically for buyers who can handle a monthly payment but don’t have a large down payment sitting in savings.
THDA Great Choice Loans
The Tennessee Housing Development Agency (THDA) offers the Great Choice Home Loan – a 30-year fixed-rate mortgage for eligible buyers that can be paired with Great Choice Plus down payment assistance. Borrowers can choose a deferred, 0%-interest forgivable second mortgage of $6,000 or $10,000, or an amortizing second mortgage for up to 5% of the sales price, capped at $15,000.
Assistance for Veterans and First Responders
The THDA also runs the Homeownership for the Brave program, which provides reduced interest rates for military veterans and active-duty service members. It waives the first-time homebuyer requirement entirely, so eligible Morristown residents who’ve served don’t have to clear that particular hurdle to qualify.
How to Compare Lenders
Morristown’s average sale-to-list ratio currently sits at 97.8% – most homes are selling very close to asking price. There isn’t much room to negotiate the purchase price down, which means your financing terms are one of the few real levers you have on monthly cost.
Request Loan Estimates from multiple lenders and put them side by side: interest rate, APR, origination fees. A fraction of a percentage point difference in rate can translate to thousands of dollars over a 30-year term. It’s worth the time it takes to make a few calls.
Local Credit Unions vs. National Lenders
National banks and large online lenders spend a lot on advertising – that doesn’t mean they’re offering the best deal. Local credit unions and community banks in East Tennessee sometimes come in with better rates or lower fees for their members. They also tend to have a working familiarity with the Morristown market and local tax structures, which can smooth out the underwriting process.
Working with a Mortgage Broker
Rather than applying directly with a single bank, you can work with a mortgage broker who shops your file across multiple wholesale lenders. Brokers can often surface specialized products or better rates for borrowers with less straightforward financial situations. Ask upfront how the broker is compensated – you want their incentives pointing toward finding you the lowest rate, not the loan that pays them the most.
Frequently Asked Questions
How do current mortgage rates in Morristown compare to the Tennessee state average?
They’re generally the same. Mortgage rates in Morristown track closely with the Tennessee state average, which sits around 6.7% to 6.75% for a 30-year fixed loan as of August 2026. Local lenders use the same national market data and state-level risk profiles to price their loans.
Are there first-time homebuyer programs in Morristown that offer lower interest rates?
Yes. The THDA offers the Great Choice Home Loan, which provides competitive fixed rates and can be paired with down payment assistance. The Homeownership for the Brave program also offers reduced interest rates specifically for veterans and active-duty military.
Do local credit unions and community banks in Morristown generally offer better mortgage rates than national lenders?
It depends on your financial profile and the institution. Local credit unions sometimes offer lower rates or reduced fees for their members compared to large national banks. Request Loan Estimates from both local and national lenders and compare the APRs directly before you decide.
Do homes just outside the Morristown city limits qualify for zero-down USDA loans with fixed rates?
Yes, many properties in rural Hamblen County qualify for USDA financing. USDA loans offer fixed interest rates and require zero down payment, though eligibility comes down to household income and the home’s specific location on the USDA eligibility map.
How long can I lock in my mortgage rate while searching for a house in the Morristown market?
Most lenders allow you to lock a rate for 30 to 60 days once you have an accepted offer. Since homes in Morristown are currently spending about 103 days on the market, you typically have enough time to finalize your loan without needing an extended rate lock.
If interest rates drop after I go under contract on a Morristown home, can I adjust to the lower rate before closing?
It depends on your lender’s policies. Some lenders offer a float-down option that lets you capture a lower rate if market averages fall before you close. Ask your loan officer whether that feature is available and whether it comes with an additional fee.


