 Facebook
 X
 Pinterest
 Copy Link
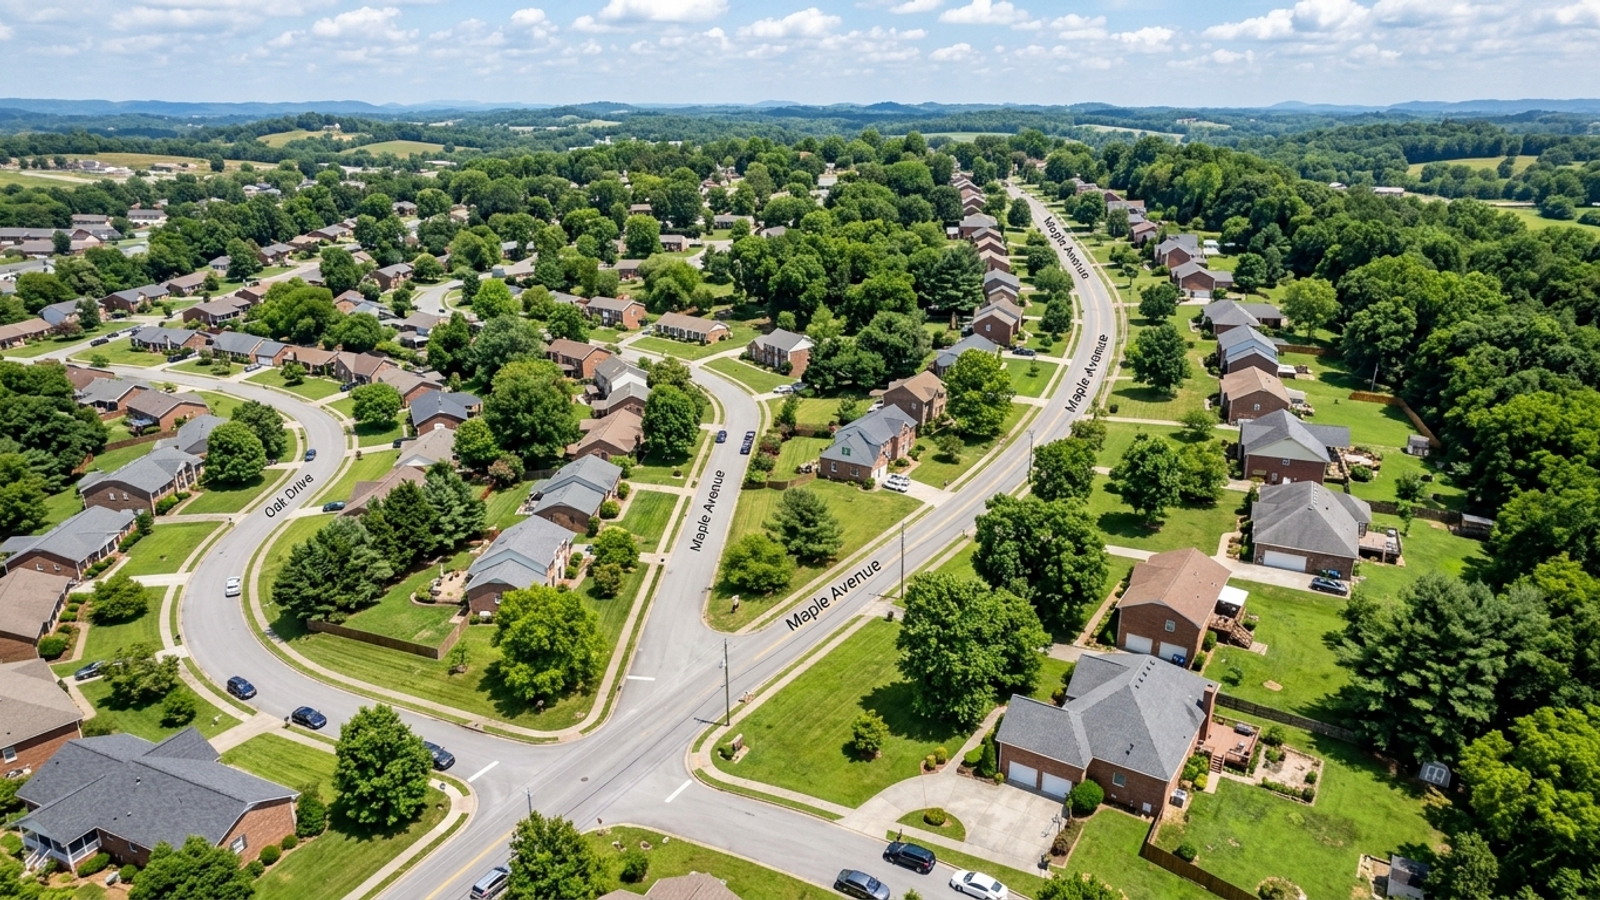
Your homebuying budget isn’t something you can figure out by glancing at a paycheck stub. As a first-time home buyer in Morristown, TN, you need to account for Hamblen County tax rates, state insurance averages, and your own debt picture before you have a real number to work with.
The current median home sale price in the area sits around $308,000. That’s a useful starting point, but your actual purchasing power comes down to your existing debts, your available down payment, and the specific property you’re buying.
Understanding Home Affordability in Morristown
Lenders look closely at your gross monthly income and your existing debts before they’ll approve anything. They’re running standardized formulas to confirm your new housing payment won’t swamp your cash flow.
Gross income – what you earn before taxes and payroll deductions – is where those calculations start. From there, underwriters subtract your current monthly obligations: car loans, student debt, credit card minimums. What’s left determines your maximum allowable mortgage payment.
The 28/36 Rule Explained
Most mortgage professionals use the 28/36 rule as their baseline. The idea is simple: spend no more than 28% of your gross monthly income on housing costs, and keep total debt payments under 36%.
Housing costs here means principal, interest, property taxes, and insurance. If your household brings in $6,000 a month before taxes, the 28% cap puts your ideal housing payment at roughly $1,680.
Calculating Your Debt-to-Income Ratio
Your Debt-to-Income (DTI) ratio compares your total monthly debt to your gross monthly income. Add your proposed mortgage payment to your existing debts, divide by gross income, and that’s your DTI.
The 36% mark is common, but some loan programs will go higher. That said, a lower ratio gets you better rates and leaves breathing room when something unexpected comes up.
Local Factors Affecting Your Budget in Hamblen County
National affordability calculators use generic estimates for taxes and insurance. Those numbers can throw your budget off in ways you won’t notice until you’re looking at a loan estimate.
Whether a home sits inside Morristown’s city limits or out in the county makes a real difference in monthly carrying costs. Lock down the localized figures early and you’ll avoid the unpleasant surprises later.
Property Taxes in Morristown
Hamblen County has an effective property tax rate of roughly 0.46% of a home’s assessed value. On a home assessed at $188,800, that works out to about $863 per year in county taxes.
Properties inside Morristown’s incorporated limits carry a combined city and county rate. Verify the exact tax history on any property you’re seriously considering – city services add to that annual number.
Homeowners Insurance in Tennessee
Tennessee runs about 42% above the national average for homeowners insurance. Recent 2026 estimates put the statewide average premium somewhere between $3,408 and $3,757 per year.
Rates have climbed sharply over the past few years. Get quotes from multiple local agents during your search – don’t rely on a placeholder figure when you’re running your monthly payment math.
Current Home Prices in the Morristown Area
As of mid-2026, the median sale price in Morristown is approximately $308,000. There are about 121 active listings in the market right now, which gives you a reasonable pool of options to work through.
Homes are sitting a median of 103 days before selling, and they’re closing at roughly 97.8% of list price. That means you generally have some room to negotiate – you’re not walking into bidding wars on every listing.
Median Home Prices
The $308,000 median tells you that half the homes sell above that number and half sell below. If you’re looking at newer construction or larger lots in Hamblen County, expect prices well above that midpoint.
If your max approval is $250,000, you’ll be looking at smaller footprints or homes that need cosmetic work. Knowing that upfront saves you from falling in love with something that was never in your range.
Down Payment Expectations
Your down payment directly reduces your loan amount, which changes everything downstream – your monthly payment, your interest costs, your insurance requirements. Conventional loans typically require 3% to 5% down; FHA loans require a minimum of 3.5%.
A larger down payment lowers your monthly payment and cuts your long-term interest costs. Put down less than 20% on a conventional loan and you’ll also need to budget for private mortgage insurance.
Hidden Costs of Buying a Home in Morristown
The purchase price and down payment are just the most visible pieces. You’re also bringing cash to the closing table before you get the keys, and once the home is yours, every repair and maintenance cost falls on you.
Budgeting for those immediate and ongoing expenses is what keeps closing day from wiping out your savings.
Closing Costs
Buyers in Tennessee typically pay about 3.63% of the purchase price in closing costs. On a $308,000 home, that’s roughly $11,180 due at signing.
That covers lender fees, title insurance, appraisals, and prepaid property taxes. Sellers carry their own set of costs – usually between 6% and 10% of the sale price for agent commissions and related fees.
Maintenance and Repairs
Owning a home means budgeting for upkeep whether you planned for it or not. The standard rule of thumb is 1% to 2% of the home’s value set aside each year for maintenance.
Older homes in Morristown can demand immediate attention – HVAC systems, roofs, plumbing. A dedicated repair fund is what keeps those inevitable expenses from blowing up your monthly budget when they show up.
Frequently Asked Questions
What salary do I need to make to afford an average-priced home in Morristown right now?
It depends on your current debt, down payment, and interest rate. To comfortably afford the median $308,000 home in Morristown, lenders will look at your gross monthly income and apply standard formulas like the 28/36 rule to make sure your housing costs stay manageable. You’ll also need to account for the roughly 3.63% in closing costs due at signing.
How much should I budget for Hamblen County property taxes when calculating my monthly payment?
Base your estimate on the county’s effective tax rate of approximately 0.46% of the home’s assessed value. For a home assessed at $188,800, county taxes run about $863 per year. If the property is inside Morristown’s city limits, expect a higher combined rate.
Are there any first-time homebuyer programs or USDA loans available for Morristown properties?
It depends on the specific property and your financial profile. Buyers often explore FHA loans that require a 3.5% down payment, but you’ll want to sit down with a local lender to find out which state or federal programs apply to your specific Morristown purchase.
Should I get pre-approved by a local Morristown lender before I start looking at houses?
Yes. A lender will calculate your exact Debt-to-Income ratio and verify your gross monthly income to give you a firm budget. That prevents you from touring homes that were never realistically in your range.
Is it currently more affordable to rent an apartment or buy a starter home in Morristown?
It depends on your timeline and available cash. Buying requires upfront funds for a down payment plus the 3.63% average Tennessee closing costs, and ongoing maintenance on top of that. Owning does let you build equity over time rather than paying a landlord – but only if the timing works for your situation.
If a Morristown house is listed at the top of my budget, do I need to leave room for a bidding war?
Not necessarily. Homes in Morristown are currently sitting a median of 103 days on the market and selling at an average of 97.8% of list price. Buyers generally have room to negotiate without facing intense competition on every listing.


